You are currently browsing the category archive for the ‘Global Crisis Blog’ category.
Global Crisis/Innovation Blog
Productivity: Good News or Bad News?
By Shlomo Maital
There are endless numbers of awful good news/bad news jokes. Here is one of the worst. Doctor: I have good news and bad news. Patient: What is the good news? Doctor: You have 24 hours to live! Patient: THAT’S THE GOOD NEWS! WHAT IS THE BAD NEWS? Doctor: I forgot to call you yesterday.
In today’s global economy, productivity growth is one of those jokes. The good news is that unlike all other global or local recessions, productivity in most countries has continued to grow strongly. The reason: Companies have been very quick to fire or lay off workers, right from the start, and the remaining workers, fearing for their jobs, have worked far harder and far smarter.
This is also very bad news. Why?
It is true by definition that GDP growth is identically equal to a) the rate of growth in GDP per worker (labor productivity) plus the rate of growth in the number of (employed) workers. If labor productivity grows as fast as GDP, then there is no need to hire more workers. And that is precisely what is happening, in the US, Europe and China.
The data? The IMF has revised its 2010 GDP growth forecast upward for the world, to 4.1 percent. Good news. Almost all of that growth will come from productivity growth, rather than from new hires. Bad news.
In China labor productivity growth for 2010 is forecasted to grow at an astonishing rate of 7.7 per cent. GDP will grow by 8 per cent. That means that employment will barely grow at all. The upside of this is that employment will at least remain steady, without massive layoffs. The downside is that there will be few new jobs for migrants coming from the West.
In the US, 2nd Q. 2010, business-sector output grew by 3.7 per cent (good news) and all of that increase came from increased productivity (bad news for workers).
The implication for individuals all over the world, especially young people entering the labor market or planning to, is rather cruel: Darwin’s survival of the fittest has come to global labor markets. In future, you will have to navigate your skills flexibly and rapidly, change them often, learn new skills and abandon old ones, and stay a step ahead of the rapidly changing labor and goods markets. Those who fail will be unable to find gainful employment, and if they remain stuck in old patterns and old skills, they may never work again.
Innovation Blog
Innovating During/After a Recession: A Three-Pronged Plan
By Shlomo Maital
Global managers need to come to terms with the fact that the ‘recovery’ will be weak, perhaps indistinguishable from recession. Whether GDP in the US and EU grows at 1% or 1.5% is immaterial. It still means that for many businesses sales will remain flat – unless the ‘three-pronged plan’ proposed by Dartmouth’s Tuck Business School Professor Vijay Govindarajan is implemented (or at least, a version of it.)[1]
First Govindarajan recommends setting up a Dedicated Team, dedicated solely to the goal of strategizing the post-recession period. Let the team come up with an innovation, and then implement it as they would conduct a scientific experiment. Why? Because until you get that innovation out into the hands of users, you will lack vital information.
Second, he recommends three steps:
• Formalize the experiment. List hypotheses. Define how you will test them. For instance: In a post-recession period, price sensitivity remains high. Hypothesis: “We will test a very low-end product with low price, and check very carefully whether demand is price sensitive, so that volume increases more than price falls, to compensate for the lower prices. Our hypothesis is that it will.”
• Break down the hypothesis. Simplify! Identify the most crucial hypothesis, or hypotheses, and focus on them. Is it price? Is it some new feature that is being added?
• Seek the truth. Jim Collins calls this “face the brutal facts”. Innovators who invest the company’s hard-earned cash have a vested interest in putting a rosy glow on test data. Make sure the company has a pervasive culture of ‘telling the truth’. Companies that delude themselves will pay heavily. Remember, if you launch full-scale a bad product, not only will the product fail, but you have lost valuable time that could have been invested in launching a successful product.
Govindarajan again stresses the obvious point that innovation is more about implementation than inspiration. While readers may be utterly tired of hearing this again and again, it is so important that it is worth repeating, in his words:
“There is too much emphasis on ideas and not nearly enough on execution. As a result, most corporations have more ideas than they can possibly move forward. Too many promising ideas on paper never become anything more than … promising ideas on paper.”
Screen your ideas, pick one or two, set up a team, give it some money – and execute. Make sure you take seriously a scenario in which there is weak economic growth for several years to come.
[1] Bloomberg Business Week, “How to innovate after a recession”, Viewpoint September 7, 2010
Global Crisis/Innovation Blog
Why America Needs a Capital Budget
By Shlomo Maital
Facing the threat of a double-dip recession, as the U.S. economy again slows and joblessness remains stuck at about one worker in 10, President Obama has brought new proposals to Congress. One of them is a program for investing in infrastructure – roads, railways, airport runways – through an Infrastructure Bank. According to Bernard Schwartz and David Rothkopf, writing in Financial Times,
“All of the president’s ideas are solid ones with broad potential benefits. In our view, among these, an infrastructure bank is particularly promising and has been misunderstood in many of the initial responses. It is so central to what the US requires at present that voters and leaders in both parties need to examine it carefully and find a way to bring it to fruition.”[1]
Here is the problem Barack Obama and the Democrats face. They spent $1.2 trillion in “fiscal stimulus” and bailouts, and the American people perceive that a large part of this money was wasted, because, it is a fact, the economy has not recovered despite this massive spending, yet the American people will now suffer the ‘hangover’ from it – paying back the debt that this program created. No-one likes to pay a debt for something that gave no value.
The Republicans are taking full advantage of this. Hence, at a time when the economy needs more government stimulus, it is doubtful the Congress will agree to it, especially not before the Nov. mid-term elections.
Is there an innovative solution?
Why not simply redefine, restructure and rethink the massive U.S. federal budget? Why not separate government spending into two parts: Current and Capital. Current spending, on things that are used up in a year or so. Capital spending, on things that create assets that yield future income. This includes investment in physical capital (bridges, roads, railroads), and human capital (education, schools). Against current spending, no borrowing should occur. Such spending will not generate assets whose income can pay off the debt. But against capital spending, borrowing is allowed, because such spending does generate yielding assets that generate the income needed to pay principal and interest.
Will the American people buy this? I believe they will. Businesses do their budgets this way. And well-run countries should be managed like businesses. Americans can understand the difference between wasting billions on bailing out GM and Chrysler, and spending money on modernizing the moribund air traffic control system or putting in an additional runway at Boston’s Logan Airport. Show them the numbers clearly and accurately, explain them, and I believe they will understand and agree. Perhaps even a change in politicians thinking will occur. By creating a capital budget, there will be a strong incentive to starve the current budget and feed the capital one. Which is precisely the kind of long-run policy America and its run-down physical capital need.
[1] “The right plan to tackle America’s crises”, www.ft.com, Sept. 8/2010.
Global Crisis Blog
Saving America: What Ronald Reagan Would Do
By Shlomo Maital
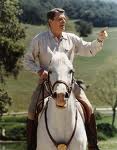
Ronald Reagan: Not your ordinary cowboy!
Suppose, theoretically, America is in deep deep trouble. Suppose, theoretically, the economy is barely growing and suppose you need at least 2-3 per cent growth to keep unemployment from rising above already high 10 per cent levels. [Why? Because productivity, output per worker, is growing at 2-3 per cent. So the economy can grow that fast without businesses hiring a single new worker!]. Suppose, theoretically, that President Obama (mis)-advised by his advisors is cutting government spending rather than increasing it, firing teachers and other superfluous public workers.
Is there anything economists can suggest, that can solve the problem?
As Isaiah said, “come, let us reason together.” When was America deep in recession? 1980-82. Who was president? Ronald Reagan, the B-movie actor who was widely mocked – and ultimately, greatly beloved. What did he do? He worked to limit imports, by forcing Japan (America’s China of the 1980’s) to accept VER Voluntary Export Restraints on its car exports to America, limiting them to 1.68 m. vehicles annually. And note, this was at a time when America had total automotive imports of $31 b. (1981).
The result was that Japanese companies (Honda, Mazda, Toyota, Nissan, Mitsubishi) were producing substantial numbers of cars in America by 1990. This created well-paying jobs for Americans, and even exports (a car made in Honda’s Marysville, Ohio, plant, and shipped to Japan, is an American export).
From 1982 through 1991, America enjoyed strong economic growth, peaking at 7.2 per cent in 1984, growth that today seems unattainable. Part of this growth was due to limiting imports.
Fast forward to 1992. Bill Clinton becomes President, and is re-elected in 1996. From 1992 to 2000, America’s automotive imports balloon from $91.5 b. to $195.9 b., more than double! For vehicles alone, the import surplus in 2000 is $110 b.! That alone lops one per cent off US GDP growth. Clinton takes no action. Yes, this is the President Clinton who insisted that America, the inventor of globalization, was a big winner from it. Tell that to unemployed auto workers.
China has been unwilling to allow its currency, the yuan, to appreciate. Its yuan is undervalued by half, making its import prices half of what they should be. Okay, use the Japanese VER card. Tell China: Restrain your exports to America – those thousands and thousands of containers that go to Wal-Mart — or we will slap a tariff on them! Horrors, you say. A gross violation of World Trade Organization rules! Sure. So is China’s currency manipulation – far far worse. But horrors! China will retaliate. China will restrict its imports from America.
Well – what imports? Paper for recycling?
Once, there were American presidents who knew how to make policy, even though they were not silver-tongued. Today we have an American president who gets A+ on oratory, but not even C- on action. This is not only America’s problem, but the world’s.
Global Crisis/Innovation Blog
Global Crisis as an Oil Spill: Let’s Help Nature and Evolution
By Shlomo Maital
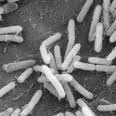
Oil eating bacteria
BBC reports today that the army of scientists researching the oil spill in the Gulf of Mexico have found that oxygen levels in the Gulf (normally excessively high after an oil spill dumps tons of hydrocarbons into the water) have not risen as much as expected.
Why? It turns out that deep in the Gulf, oil-consuming bacteria have been proliferating rapidly and have been gobbling up the bad sticky goo. Normally, such bacteria are few and far between. But suddenly, when their food supply expands a thousand-fold, they leverage their bounty by multiplying. It is Nature’s way, and evolution’s way, of dealing with nasty surprises.
When the sticky oil has been eaten up by the bacteria, who transform it into energy needed to grow and to reproduce, the existing bacteria will run out of food. They will die off, and their numbers will fall back to what they were before the oil spill.
It occurs to me that the Global Crisis 2007-9 is very similar. Financial services firms of all kinds (Fannie Mae, AIG, Goldman Sachs, speculators, hedge funds, private equity, VC’s) all proliferated, like bacteria, when their ‘food supply’ suddenly became rich and plentiful (booming capital markets fed by the ‘oil spill’ of Alan Greenspan’s low-interest come-and-get-it-while-you-can money and credit).
Now that ‘food supply’ has dried up, mostly, and all those ‘financial services bacteria’ (no, I will not call them ‘germs’) will perforce shrink and decline, as they should. At least, they will, if we behave rationally. If we act to preserve them, as Geithner and Obama have, we are simply creating another oil spill, probably a worse one.
Often, after terrible wildfires, Nature appears utterly destroyed, burned. In an amazingly short time, green shoots appear; indeed, some plants and trees need the fire in order for their seeds to germinate. Similarly, in the Global Crisis, those green shoots can and will reappear, if we let them. But if public policy is bent on preserving the deadwood, there will be no air and water and earth for green shoots.
Global Crisis/Innovation Blog
How Internet Brings People Closer Together
By Shlomo Maital
In his seminal article 43 years ago, psychologist Stanley Milgram showed how very small our world is, in his Small World experiment. [1] Milgram showed we are only, on average, six ‘degrees of separation’ apart from one another.
According to Wikipedia: Six degrees of separation (also referred to as the “Human Web”) refers to the idea that everyone is at most six steps away from any other person, so that a chain of, “a friend of a friend” statements can be made to deliver a package from one person to any other randomly-chosen person in six steps or fewer.
Now come several new studies showing how the Internet has sharply reduced those six degrees to three or fewer.
- In 2001 a Columbia University Professor, Duncan Watts, used an email as a ‘package’ and found , with 48,000 senders and 19 targets in 157 countries, the average number of intermediaries was six.
- The average distance on Twitter (based on a study of 5.2 billion ‘relationships’ when Twitter users follow other users) is 4.67.
- Twitterers, or Tweaters, who also belong to the 14 largest Yahoo groups have only 3 degrees of separation.
- Yahoo Groups, in turn, the world’s biggest online discussion boards, have 150 million members, and 10 million groups, in 25 languages. This is perhaps even more surprising than Facebook’s 500 m. users, because Yahoo’s discussion groups create meaningful conversation, communication and interaction. The biggest are “Athenians”, “Pure capitalism”, “Capitalists forever”, “globaltaxrevolt”, “blowback”, “clearcutforum”, “fireflyflash”…etc.
Milgram’s original study got a package from someone in the American Midwest to a pastor in Cambridge, MA. Today, we can get an email message from anyone, anywhere, to anyone else, anywhere, in about the same number of handoffs.
In this smaller shrunken world, will the Internet ultimately foster the idea that all of us are brothers and sisters, regardless of ethnicity, race or religion, and that we can use technology to achieve deeper human understanding?
Will the tendency of our political leaders to lead us into conflicts and wars be replaced by the tendency of ordinary people surfing the Web to seek understanding and peace?
[1] Stanley Milgram, “The Small World Problem”, Psychology Today, 1967, Vol. 2, 60-67.
Global Crisis/Innovation Blog
Lost Generation of Youth: Is Entrepreneurship the Solution?
By Shlomo Maital
The phrase “lost generation” appears in the epigraph to Hemingway’s great 1926 novel The Sun Also Rises. The phrase was coined by Gertrude Stein, who got it from a Paris garage mechanic (he called the post WWI generation, une génération perdue).
A new lost generation is emerging from the 2007-9 Global Crisis – youth unemployed. In Bloomberg Business Week (“Viewpoint”, Aug. 10) Chris Farrell notes the jobless rate for Americans aged 16-19 has jumped to 26 per cent, part of “the worst job market in 60 years”. And writing in the Global New York Times, Matthew Saltmarsh (“Global Youth Unemployment Reaches New High”, August 11) paints a much bleaker picture all over the world.
Farrell notes, “…among some minority groups the high school graduation rate is low: about 55 percent for Hispanics and 51 percent for African Americans, vs. the U.S. total of 69 percent, according to 2005-06 data….’You are really creating a society of people who don’t know what work is like,’ says Robert Straits, director of the Employment Management Services Div. at the Upjohn Institute for Employment Research. ‘It’s a generation of people who have never held a real job.’”
Saltmarsh reports: “…the International Labor Organization, said in a report that of some 620 million young people ages 15 to 24 in the [global] work force, about 81 million were unemployed at the end of 2009 — the highest level in two decades of record-keeping by the organization, which is based in Geneva. … Spain had a jobless rate of 40.5 percent in May for people under 25. That was the highest level among the 27 members of the European Union, far greater than the 9.4 percent in Germany in May and 19.7 percent in Britain in March.”
What can be done? What MUST be done?
Part of the problem is geography. Poorly-educated youths are mostly in inner cities, while entry-level low-skill jobs are far out in the suburbs. But much of the problem is simply supply and demand – creating a supply of key job skills to match demand. Germany has low youth unemployment partly because its superb vocational high schools equip youths for manufacturing jobs, and then Germany’s business model produces those jobs through competitive advantage and export success.
I wonder if an experimental program could be attempted, in which youths are taught the fundamentals of starting a business (delivering hot fresh-baked rolls early in the morning to lazy suburbanites), then given some micro-finance to get rolling. Even one success out of ten that creates ten jobs will overcome the other nine failures.
It is unacceptable that young people should be doomed even before they truly begin their lives. It is unacceptable to have a “lost generation”, when Wall St. fat cats are bailed out with government money that could have been used for job creation. And it is incredibly unacceptable that the world accepts the growing “lost generation” with equanimity, without loud political protests. Perhaps if we gave the vote to 16-year-olds, they might have a voice.
Here is some food for thought. The heading is “social insanity”.
In the US it costs $20,000 a year to keep a person in jail. In Florida, fully 8.5 % of the state budget goes to “corrections” (jails), or $2 billion ! Suppose, just suppose, one in ten of the unemployed youths ends up in jail. Suppose he or she serves, during a lifetime, a 10-year sentence. That’s $200,000 in direct costs, not counting the huge damage done to victims. The expected cost, then, is 1/10 times $200,000 or $20,000, not counting human suffering. Would it not make sense to invest $20,000 in prevention, for each unemployed youth, to keep the youths out of jail, by giving them skills and a livelihood ? Is there any other term for it, other than “social insanity”, for spending $2 b. on jails instead of $2 b. on a youth jobs programs?
Global Crisis Blog
The Next Crisis: How a Headline Can Deceive
By Shlomo Maital
Can Israel anticipate the next global crisis in time to act to avoid it?
On Aug. 3, all of Israel’s daily papers reported good news about exports. The headlines screamed: “India leaps to No. 2 export destination”. Data from the Ministry of Industry, Trade and labor showed that in the first half of 2010, exports to India rose to $990 m., second only to exports to the U.S. and up from 8th place in the first half of 2009. Exports to China climbed from 11th place to 5th place. Conclusion: Exporters have been targeting the fast-growing markets of Asia, while U.S. and European markets “have stayed firm”. Good news.
So where is the crisis? It is hiding – under a load of “fertilizer” (India sharply boosted its purchases of Dead Sea chemicals and fertilizer). A third of Israel’s exports go to Europe, and 28 per cent to the U.S. These two key markets are about to decline sharply. Together they comprised about $10 b. of Israel’s exports in the first half of 2010. The table accompanying the glowing report of success contains the real story: Israel’s vulnerability to economic decline in its two main markets, America and Europe.
Global markets are supposedly going through a transition, known as “rebalancing”. In this process, Americans save more, spend less, borrow less, export more and import less, while Asia (mainly China) saves less, spends more, imports more and exports less. This will rebalance the global economy, which crashed when imbalance – money poured out of the US, goods poured in, mainly from Asia – ruined it.
This is a pipe dream. Rebalancing will not happen. China’s growth model is built on exports, and its success with the model means China will not abandon it, even if it continues to lend to the Americans. Americans cannot spend less until governments slash “entitlements” (social security, health care), and politically this will not, cannot happen. Meanwhile the US economy has begun to slide again. New York Times columnist Bob Herbert reports that if you add to the official 14.6 million unemployed, the 5.9 million workers who have stopped looking for jobs, and the 8.5 million who have part-time jobs but want full-time, you get 30 million Americans who need work and cannot find it. There are 3.4 million fewer private-sector jobs in the U.S. than a decade ago. This is why Americans feel down when G.D.P. numbers are up. A slowdown has already begun.
As for Europe, it is confused, stumbling and in trouble. The stabilization fund to bail out bankrupt EU countries is a fiction and may not be renewed in three years. Europe is expert at keeping out imports to help its struggling economies.
The global system was designed to create growth. It was not designed to deal with global crisis and recession. Most countries are now engaged in budget tightening – the opposite of what is needed. Conclusion: For exporting nations (like Israel), crisis looms.
What will replace collapsing markets in America and Europe? Does Israel, and its exporters, have Plan B?
Global Crisis Blog
If You Don’t Believe Me, Ask the REAL Experts!
Why Top Economists See Crisis Looming Ahead — and “We Don’t Have Plan B!”
By Shlomo Maital
Peter Day
BBC Global Business broadcaster Peter Day recently interviewed four top economists and economic historians, all of whom have deep experience in the real world, and came away with some alarming predictions about the rocky road ahead.
The economists were: Kenneth Rogoff (formerly chief economist for the International Monetary Fund), Simon Johnson (MIT Sloan School management professor), Raghuram Rajan (Booth Business School, Univ. of Chicago, professor, who predicted the current crisis) and Sushil Wadhwani (City of London Wadhwani Asset Management fund manager, former director of strategy at Goldman, Sachs, and a member of the Bank of England’s monetary policy committee).
If you prefer not to read this overly long blog, here are a few excerpts. If they worry you, then please do read on.
“We seem to be forgetting 1937, we’re getting significant global tightening, grafted on to a tightening of the global banking system”, precisely what happened in 1937..” “We’re still winding up for another global meltdown”… “we shouldn’t delude ourself…in some ways we’ve postponed the day of reckoning.. V shaped recovery? No, it’s a V-sign recovery, we’re going to get a big shock about the hangover that this crisis has left us with”.
1. Kenneth Rogoff, Harvard U. Professor, co-author of the new book This Time is Different: “Is this crisis different? No. I think arrogance, ignorance are eternal characteristics of man Americans want to put off the day of reckoning… we should try to close up deficits in 4-5 years, convince financial markets they will do it… try to be credible, not to go too far too fast… Could there be a downward spiral, a tipping point? Absolutely, if you owe a lot of money, keep needing more, to fund new deficits or to pay back old loans as they come due, you need credibility… if financial markets decide not to lend to you….you’re greased, no-one will give you money, so governments just have to be credible, they can’t just spend and spend. The capital markets need to see there is some discipline down the road… if they see you riot in the streets when little spending cuts happen (Greece)… they (markets) can be merciless… “
2. Sushil Wadhwani: “Policy makers said 18 mos. ago, they wouldn’t make the mistakes made in 1937, or that Japan made… but we now have the tightest fiscal stance in 30 years, this could be a significant mistake..we have almost coordinated global fiscal tightening at a point in the business cycle when the global economy was set to slow anyway, because the inventory contribution was set to diminish, fiscal tightening will make the shift to consumption and investment less likely… I think this significantly increases the downside risks to this recovery… my real worry is, we don’t seem to have a plan B. Support for fiscal tightening …we can’t suddenly reverse it… interest rates are already very low, quantitative (monetary policy) easing effects are unproven…in economies with debt hangover where an asset bubble has burst it is hard to get monetary policy to be effective…we are now vulnerable, if a horrible event tips us into a recession, the markets will start worrying there is no policy ammunition left. Policy makers have no Plan B!! Three things could go wrong. a) The Greeks could decide to restructure their debt before 2012, if no firewall is in place, this could be problematic, b) Europeans have announced a 750 b. Euro stabilization package, but we all know the money isn’t really there, it includes the German quota from
the IMF, and contributions from Spain, Italy, Portugal, which may not be there… c) in 3 years time, the stabilization mechanism expirres, and the renewal date is just a few months before the German election… there is no Plan B”.
“It is sad we are not learning the correct lesson, people are not always wiling to admit to mistakes, there is not enough contrition being shown. We are not reforming the system in the way it needs to change. Wall St.: the banks have recaptured the system, gotten off lightly so far, they have political clout. Central Banks have not observed the appropriate lessons, not even willing to admit to their mistakes, same is true of financial regulators who made grievous mistakes, there were plenty of warnings around, not just stopped clocks in the private sector…Central bankers of smaller countries regularly warned the big Central Banks. In larger countries, no one paid attention… e.g. Sweden, Australia, Norway…they frequently warned their colleagues, no attention was paid, the opposite: e.g. in 2001 in a G10 working party, what should be done with financial regulation? Chair was the Gov. Of the Swedish Rijksbank, he made impressive recommendations, US and UK suppressed the report, it came out only as a think tank report…it got in the way of free markets, so it was not what the US and the UK wanted then. There were plenty of warnings. It was a classic bubble. Hard to know when and how it bursts, but it is clear that at some point it will go awry, we relied on the Greenspan mopping up doctrine, we could deal with it afterward, even though history shows mopping up doesn’t work. “
3. Raghuram Rajan “Banks got themselves into such a mess, governments had to bail out system. They are now at the mercy of the verdict of the same financial markets. There is an unholy nexus. The Political Left wants to see bankers as the problem. The Political Right wants to see the government as the problem. The fundamental problem of capitalism is: how to get them to work together in a way that is sensible, with bankers not feeding off govt. and vice versa…govt. in US wanted a political goal, more lending to low-income segments, bankers took advantage of this and made a ton of sub-prime loans and got into trouble, govt. came to their rescue with bank bailouts… this is an unholy nexus, taken to the next stage, banks now hold a significant portion of govt. debt, govt. And govt. is the backstop for the banks..this is where we need to figure out how to break the bank/govt. nexus. Small steps in financial sector reform are not enough.”
4. Simon Johnson (author of The Baseline Scenario, a widely-read blog and co-author of 13 Bankers: on the way banks have the whole American system in their bear hug…)
“We have 2,400 pages of Financial Reform Act legislation, very little of it will make any difference, the lobbyists have done a terrific job… it won’t reduce risk as we go forward in the next cycle. The next bailout could be bigger… as a Greece scenario, you can’t afford to do a bailout, too big to fail becomes too big to save…very bad further outcomes, Great Depression…nowhere is it written you can’t repeat the 1930s, you can, if you let the financial system go mad… There’s enough debt to be dangerous,we don’t even know its dimensions, derivatives are opaque, have been secretive, we don’t know if derivative positions would limit the damage of an asset crash or amplify it… you only find out, the Minister of Finance only finds out a few hours before the decision of bailout or bust.
“Is Chinese growth a global trump card? The G20 hopes so. At their last summit, they said, expect everyone to engage in austerity, but we don’t think it will lead to serious downturn, something good will happen to offset it — growth in China. In China they are trying to cool things down. Chinese academics, those who study the Chinese economy, they were sceptical about China. … Is a Third Great Depression is looming? There may be a financial boom, not so good for regular people, and another form of debt cycle, expansion, funded by inflow of capital, mostly debt, things will go well for a while, optimism everywhere, you won’t interview us negative peole, and then, another crash — how big, how damaging? The financial system is too big, it doesn’t help, it only transfers money from us to the financial sector, but it has political power that is resisting reform, politicians if they try to reign in financial power, think it will cause economic disaster — but the exact opposite is the truth!”
Peter Day. “History teaches us something is wrong here, but I doubt many of us know what it is.”
Global Crisis Blog
“Cash for Clunkers” Was Itself a Clunker
By Shlomo Maital
Ford Explorer 4WD: Most popular “cash for clunkers” vehicle – green? fuel efficient???
America’s “Car Allowance Rebate System” (CARS), or “Cash for Clunkers” was a $3 b. fiscal stimulus program giving Americans each $4,500 for scrapping old cars and buying new ones. The program began officially on July 1/2009 and ended on Aug. 24. When the initial $1 b. appropriated by Congress was exhausted, an additional $2 b. was allocated.
Of the new cars sold under the program, Toyota sold 19%, GM 18%, Ford 14%, Honda 13% and Nissan, 9%. Japanese and Korean car companies gained significant market share as a result of the program, at the expense of embattled American firms. (A similar program in Japan excluded US vehicles.) According to Wikipedia, “a study published after the program by researchers at the University of Delaware concluded that for each vehicle trade, the program had a net cost of approximately $2,000, with total costs outweighing all benefits by $1.4 billion.”
Democratic politicians claimed Cash for Clunkers was a big success, citing all the new car purchases it created (690,000 dealer transactions). But writing in The American, the journal of the American Enterprise Institute (a right-wing pro-free-market think tank), Max Borders lists 10 separate reasons why the program was a major badly-planned failure.
1. The policy concentrated benefits on political interests. Because the stimulus focused on the auto industry, many wondered whether the policy was a means not only to rescue a bloated, wasteful U.S. auto industry, but to pay back the unions—particularly the United Auto Workers—for their support for presidential candidate Barack Obama and the Democratic Party in the 2008 election.
2. The policy had the effect of sucking revenues from other industries ailing from recession. In other words, if people are paid to spend money on cars, they’re less likely to spend money in other sectors.
3. The policy destroyed goods that had value, which means it destroyed value. Professor John Quelch of Harvard Business School writes: “A $2,500 incentive would have attracted the older, most fuel inefficient used cars. Instead, a $4,500 incentive attracted many perfectly serviceable vehicles. Because of government concerns over fraudulent recycling of trade-ins, vehicles had to be destroyed.”
4. The policy distorted the used-car market by reducing the availability of cars desired especially by the working poor. Why, in the middle of a recession, would anyone want to drive up the price of goods used by society’s most vulnerable people?
5. The policies’ stated goals, if met at all, were met inconsequentially. Shikha Dalmia, writing for Forbes, shows improvements in air quality and fuel savings were virtually undetectable: “Even if one accepts [Transportation Secretary Ray] LaHood’s numbers, the fuel savings add up to only 72 million fewer gallons of gasoline every year—about what Americans consume in four and a half hours.”
6. The policy generated considerable opportunity costs. Even if you grossly overestimate the success of the policy, the costs of forgone uses of the resources are, though impossible to measure, still considerable. In other words, every dollar you spend on x is a dollar you cannot spend on y.
7. The policy successfully purchased a prophecy that would have fulfilled itself within two or three months. Most of the people who participated in Cash for Clunkers would have bought cars soon anyway. As car review company Edmunds famously pointed out, the policy shifting buying patterns forward a few months at most. Here are the results: “Nearly 690,000 vehicles were sold during the Cash for Clunkers program, but Edmunds.com analysts calculated that only 125,000 of the sales were incremental. The rest of the sales would have happened anyway.
8. The policy subsidized people to make unwise purchases. It may take more time to determine this fallout, but—like subprime mortgages and artificially low interest rates—some people had incentives to get into cars they would have wisely avoided.
9. The policy allowed politicians to claim success despite failure. When any macro-economic policy measure is complicated and convoluted, it’s easier to obscure what goes wrong. This is exactly what Congress and the Obama administration did in this case. A lot of politicians deluded themselves so thoroughly that Congress went back for another round, extending the program.
10. The policy was an old-fashioned wealth transfer. “A and B put their heads together to decide what C shall be made to do for D” wrote William Graham Sumner in 1883. “The radical vice of all these schemes, from a sociological point of view, is that C is not allowed a voice in the matter, and his position, character, and interests, as well as the ultimate effects on society through C’s interests, are entirely overlooked. I call C the Forgotten Man.” But let us not forget C. Government resources come from somewhere, as did the cash for all those clunkers.