You are currently browsing the category archive for the ‘Global Crisis Blog’ category.
Global Crisis
Financial Times’ Martin Wolf Clears the Fog: Why You Should Read Every Word
By Shlomo Maital
Of all the economics columnists writing today in the financial daily press, I urge you to follow and read Martin Wolf. This prize-winning journalist is able to slice through the fog of jargon and uncertainty with sharp analysis. His style is not lively or filled with metaphors. But please, persist. If you read Martin carefully, you will understand what in the world is going on.
And, yes, what in the world IS going on with Britain? Here is Martin Wolf’s ‘take’ on it, in today’s (April 14) FT issue (p. 11, “Only rebalancing will revive Britain’s precarious economy”). To save you time I will “interview” Martin and summarize his argument, adding some points of my own.
What is a ‘balanced’ economy?
One in which money taken out of the system in saving is offset by money put back into the system, as demand, by government, exporters, consumers and businesses, creating just enough demand for growth and full employment without inflation.
Does the U.K. enjoy this balance now?
Not at all. Households have a net savings surplus. So do businesses (they spend less than they earn). Government, though, has a big deficit. It has to borrow one pound for each four it spends. This creates massive debt which rattles capital markets. More is still being withdrawn than put back in, hence Britain’s weak economy.
Why doesn’t the government cut its deficit and borrowing?
Because if it does, the recession will deepen, because — who will take up the slack in demand?
Will there be a crisis, Greece-style?
Perhaps. If private spending and exports recover to generate demand, the UK govt. can cut its deficits without ruining the economy. This would be a smooth ‘rebalancing’. If private spending, investment and exports do not recover, and the government slashes its deficits, the recession will become ‘double dip’. This would be rocky unbalancing. British Households are saving more, because they are struggling to get out of debt. The worse the deflation is, the more burdensome the debt.
Is the falling value of the pound sterling a problem?
It is for Britain’s bloated financial system. A strong pound helps it make money. A weak pound drives money away. But it is the solution for Britain’s exporters, and Britain desperately needs to boost its exports. Can the weak inefficient British manufacturing sector shape up and drive exports? Some are doubtful. Can the ‘real’ economy (exporters) overcome the sham one (financial services)? Stay tuned.
Do other countries have the same problem?
Yes. The U.S. There too, deficits created enormous debt overhang. There too, business investment and exports have not taken up the slack. There too, manufacturing is moribund. Rebalancing is as vital and as tricky in America as in Britain. It will take a very clever, steady hand on the policy rudder. As Martin Wolf puts it, “this is going to be a very tricky policy performance”. With Britain’s political system facing a divisive and probably non-decisive election, and with America’s political system more partisan than ever, with rancor between Republicans and Democrats, very little bipartisan good will can be mustered to handle this rebalancing.
The conclusion is that in contradiction to popular opinion and wishful thinking on Wall St. and among many businesses, the 2007-9 crisis is far from over. It is metamorphosing, changing its form from a banking and financial crisis to a national crisis — one where governments’ solvency itself is questioned. In some ways this is worse. Government policy has shifted from being the solution to potentially becoming the problem. If you thought the bankers were great at ruining their businesses — wait until you see what the politicians can do to theirs.
Global Crisis Blog
What We Learn from Greece’s Crisis
What can we learn from Greece’s debt crisis? This is the question raised by Paul Krugman in his recent NYT column.
(As he wrote it, the EU was waking up and coming to Greece’s aid, belatedly. Germany has dragged its feet on this bailout for months, and the euro has plummeted as a result. Germany’s position was: Why should German taxpayers bail out the Greek spendthrifts? Answer: If you don’t, Germany and all Europe will suffer.)
It is not a debt crisis, Krugman rightly observes. Greece’s debt burden is not excessive.
What is the problem, then?
It is a “I’ve painted myself in the corner” problem. Greece is in the EU, adopted the euro (abandoning the drachma) and now cannot devalue its currency to boost its economy. It is stuck with the euro. It could withdraw from the euro zone, but that would cause a huge run against Greek bonds and stocks. Greece cannot raise interest rates, because those are now set by the ECB, the European Central Bank. Greece cannot ‘inflate’ to reduce the debt burden, as other nations have done in history, because, frankly, what Greece needs to do is deflate, lower its wages, prices and costs in order to become more competitive within Europe. But if it deflates, the debt burden becomes much more onerous, rather than less so.
Even if the EU does bail Greece out in the short run, long run structural problems will remain. And Greece is not alone. Other nations, like Portugal, Spain, and Ireland, perhaps even Italy, share them. Consider America. When California has a huge real estate bubble, and goes nearly bust, there is little the Federal Govt. can do to help California specifically, at a time when other parts of America are doing better. This is the problem with an integrated economy. There are big gains to such integration (a large efficient Single Market) but big problems, when a part of the market gets into trouble.
So what can Greece do? Savage spending cuts and tax hikes, says Krugman, to slash deficits and reduce borrowing. But this would worsen unemployment and cause political crisis. We are left with a Hebrew saying: Wise people (or countries) avoid crises clever people (or countries) can get out of.
Greece is not wise. Hopefully it will be clever.
Innovation Blog
The Big Short: How Wall Street Screwed Us and Itself
By Shlomo Maital
 Michael Lewis
Sorry for the vulgar language — but, it fits the subject and it accurately reflects the views of someone far wiser than me: Michael Lewis, author of the new book The Big Short, about the global financial crisis of 2007-9.
Interviewed on the CBS News program 60 Minutes, by Steve Croft, Lewis succinctly nailed the root causes of the crisis. “Mass delusion!” Here is a summary of the interview:
“Our culture will come to the conclusion that everybody (on Wall St.) is a criminal. But the story is much more interesting. There is mass delusion.”
A handful of people saw it coming. Dr. Michael Berry, a medical doctor with Asperger’s Disease (and one blind eye, from a bout with cancer) saw it. [Ironic, someone with one eye saw things those with two good eyes failed to!]. He started a hedge fund in Cupertino, CA., and in 2005 foresaw the 2007 crisis in sub-prime mortgages. He invested in CDS (credit default swaps, insurance against bond default), betting on default — and made $720 m. ! How? He took the trouble to read the sub-prime mortgage documents, while others did not. He saw through the scam, in which Goldman Sachs investment bank persuaded AIG to issue CDS’s in the amount of $20 b., and later, another $30 b., without understanding at all what they were insuring (not a 1 in 1,000 event, but a 100% certainty of collapse, owing to the nature of the subprime mortgages). Why didn’t others on Wall St. see it? “Wall St. is paid to delude itself,” he says. Berry explains why the bonuses are so huge. “The top people there want to be paid huge sums, so they have to pay people below them very large sums,” he explains. Berry thought, when he bought up CDS’s, that others would copy him, eliminating the profit. But they did not. Perhaps 10 or 20 people acted like him, seeing the looming crisis coming.
Lewis told Croft: Wall St., in its present form, cannot be sustained. It is getting subsidized credit from the Fed, paying zero interest, then lending and investing at higher interest, and making billions. This cannot be sustained. “The (Wall St.) leaders have lost their sense of responsibility to society”, he observes. “Wall St. has become disconnected from reality, from real productivity”. It was an elegant form of theft, he believes. Wall St. bankers paid themselves $20 b. in bonuses in 2009 — after the crisis! In 2007, they paid even more: $33 b. in bonuses!
But the worst part, the least believable part? Nothing has been fixed. The bond rating agencies that rated junk as AAA (Moody’s, S&P) are still paid by the folks who issue and sell the bonds — the investment banks. And Credit Default Swaps? Well, they still are unregulated, and nobody knows to this day how much they total or what they are worth? And the icing on the cake? The same ‘experts’ who caused the crisis — are now cashing in, with huge consulting constracts for the government, because they are the only ones who really understand the garbage paper they inflicted on society. “A neat trick Wall St. does often,” Lewis notes, “charging fortunes for cleaning up the messes it created in the first place.”
What did the broadcaster Beale say, on the 1976 film Network: “I’m mad as hell and I’m not going to take this any more!”. Well, we are mad as hell — and we are, alas, taking it every single day.
Is there any consolation? Lewis has been right so far. He thinks Wall St. in its present form is unsustainable…it will disappear. Let’s hope he is right.
Global Crisis Blog
Rashomon & the Global Crisis 2007-9
By Shlomo Maital
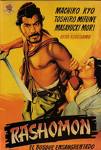
Expectedly, a spate of books is appearing, interpreting the causes, nature and effects of the global crisis 2007-9. My own book (which leverages the crisis to explain why and how managers must now think for themselves, and never again rely solely on economists) will appear in June. (Global Risk/Global Opportunity: SAGE, 2010).
It is hard to sift through the various perspectives, to find the real truth. It is much like the legendary 1950 Japanese movie Rashomon, which depicts the rape of a woman and murder of her samurai husband, through the eyes of the wife, the bandit, the samurai and the woodcutter — each account being very different, each account truly believed by the teller. As I have learned during recent study groups, even the Bible is not exempt from the ‘victor’s syndrome’ (the victor tells the ultimate story, even if it is false). The Book of Kings is written in a biased manner in favor of the Kings of Judah, severely distorting historical truth, against the Kings of Israel (the northern tribes that split away from Judah).
The latest entry is The End of Wall Street, by Roger Lowenstein, a top (the top?) Wall Street reporter. (Penguin: 2010). Reviewed by equally sharp financial reporter Joe Nocera, in the Global New York Times (April 4), Lowenstein’s book (which follows one he wrote on Long Term Capital Management) avoids clichés and focuses on the “business theories that led to grievous destructive miscalculations” (the idea that a world of highly interconnected financial systems makes regulation unnecessary and smoothes away business cycles or bubbles). My guess is The End of Wall Street will be the definitive book on the crisis, at least for many years, until the focus of time helps us overcome the Rashomon effect and truly understand cause and effect.
Innovation Blog
Vive La Charrette! Get Your Innovation Process “On the Wagon”
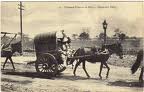
The Charrette in Paris
Innovators can profit much from a clever process finding wide use in the United States and abroad in urban planning and development. The process is known as “charrette”.
Here is how it works.
Charrettes often take place in multiple sessions in which the group divides into sub-groups. Each sub-group then presents its work to the full group as material for future dialogue. Such charrettes serve as a way of quickly generating a design solution while integrating the aptitudes and interests of a diverse group of people.
In urban planning, the charrette process is highly visual, with groups posting on walls drawings and pictures that reflect their thinking. The results are then integrated and combined. The process is not unlike that of IDEO’s “Deep Dive”.
For example:
…..the University of Virginia’s School of Architecture unofficially calls the last week before the end of classes Charrette. At the final deadline time (assigned by the school), all students must put their “pencils down” and stop working. Students then present their work to fellow-students and faculty in a critiqued presentation.
The charrette is employed by municipalities around the world to develop long-term city plans, drawing on a communal process in which ordinary citizens express their views, often by bringing pictures or drawings of neighborhoods they regard as ideal. The charrette process is time-limited — the goal is to achieve consensus on a master plan within a very short period of time, and it is collaborative, avoiding the adversial legalistic approach that can take years.
The term” charrette” comes from the French for chariot. It is said that French architecture students studying at the famous Parisian Ecole des Beaux Artes scribbled desperately to finish their final designs while riding to school “en charrette” (in a cart). An alternate explanation is this: At the end of a class in the studio, a charrette (cart) would be wheeled among the student artists to pick up their work for review while they, each working furiously to apply the finishing touch, were said to be working en charrette.
The charrette method (www.charretteinstitute.org) stresses speed and urgency, overcoming often-fatal inertia and bureaucracy. It overcomes the political obstacle of individuals pressing their own ideas by making the ultimate solution a collaborative one, to which all have contributed.
Can you build a charrette process in your organization? Why not create an actual ‘charrette’ (wagon, or ‘chariot’)? Roll it past groups, get them to place their visualizations on it, stick the results up on the wall — and then mobilize the group to integrate the ideas, back off them somewhat and create a final proposal that embodies the best features of all the various ideas. Encourage wild thinking, because ultimately, “feet-on-the-ground” wisdom will bring the ideas back to reality, in the process of integration.
Innovation Blog
The Real Truth About China’s High-Tech Industry
By Shlomo Maital
A terse and compelling background brief by Xing Yuqing, from the National University of Singapore’s East Asia Institute, reveals the truth about China’s high-tech industry. [1] Here are a few excerpts:
* China became the world’s largest high-tech exporting nation in 2006, surpassing Japan, the US and the EU-27, with 17% of global market share in high-tech products. China’s high-tech exports doubled every two years between 1995 and 2008!
* The cause of China’s high-tech export growth is “relocation of production capacities by multinational enterprises into China”; foreign MNE’s “account for 85 % of China’s high-tech exports”.
* A crucial role was played by Taiwanese-owned companies; Taiwan relocated all of its production in laptops, digital cameras, motherboards and LC monitors to China. This, despite China-Taiwan hostility. Apparently, business trumps politics.
* China “is far from being a real high-tech exporter”; so-called high-tech firms in China “are at the lowest value added segment of production chains: processing and assembling.” China imports large amounts of high-tech components.
* Despite China’s high domestic saving rate, much of China’s high-tech capacity was built and financed through FDI foreign direct investment.
* China has yet to build a true indigenous high-tech technology capacity. It is in fact an exporter of low skill labor, rather than high-tech technology.
Essentially, America and Europe have shifted their manufacturing to China. Was this wise? China leveraged its infinite labor supply to gain global competitive advantage, but is taking aim on the next stage in its long-range plan: Move up the value chain. This could be a threat to the U.S. and Europe. If it happens, it will be America and Europe that made it possible, by giving China a powerful boost up the high-tech value chain ladder.
[1] XING Yuqing, “China’s High-Tech Exports: Myth and Reality”, EAI Feb. 25 2010.
Innovation Blog
Birth and Death Among Startups, and the Rise of Necessity Entrepreneurs
By Shlomo Maital
There is controversy over whether the tendency of Israeli startup companies to ‘exit’, by being acquired by foreign companies, is good or bad for Israel. in the past three years, there has been a constant crop of such exits, about 85 a year, though their peak value ($10 b. in 2006) has declined sharply by some 75 per cent. Clearly, it would be better for Israel if those acquired companies could be scaled up to global size, creating jobs, income, wealth and exports for Israelis. But even entrepreneurs who want to achieve such scale, rather than take home a very large check, face formidable obstacles, in manpower and finance.
I believe that a bigger problem than ‘exit’ is ‘death’. There are many unobserved funerals. Of Israel’s some 3,000 startups, many are quietly closed each year. Perhaps the spotlight should be focused more on “what can be done to increase survival rates and reduce morbidity?” than on “what can be done to reduce exits?”.
What can be learned from American data? According to a study by Moya K. Mason, “Research on Small Businesses” [http://www.moyak.com/papers/small-business-statistics.html ], U.S. Census data show there were 5.7 m. US firms with employees, and 17.0 m. without employees (i.e. sole proprietor) in 2001. Small firms with less than 500 employees account for 99.7 per cent of the 23.7 m. American businesses in total. Hence, the small business sector in the U.S. is hugely important.
For businesses with employees (as noted, about 5.7 m.), there were 572,900 new firms born in 2003, and 554,800 firms that closed that year. The vast majority of those were ‘small’. So, each year, roughly 10 percent of small businesses die, and the same number are born. This process is healthy and important. It is part of what Joseph Schumpeter called ‘creative destruction’ and what Peter Drucker called “innovation and abandonment”.
Mason reports, “2/3 of new employer firms (i.e. firms with employees) survive at least two years, and half survive at least four”. About a third of firms that closed said their firm was successful at closure. That implies that the firm was likely acquired and merged into a larger firm. [1]
In America, such ‘exits’ leave their IP, assets and added value in the U.S., since the vast majority of them are acquisitions by other US firms. So an ‘exit’ in the US has different economic implications than an exit in Israel.
Worldwide, a massive study known as GEM Global Entrpreneurship Monitor finds “there are about 300 m. persons trying to start about 150 m. businesses” in the GEM countries, whose population totals 4 billion, roughly two thirds the total world population. A third of the businesses people try to launch are actually launched, or 50 m., each year, about 137,000 every single day. About an equal number of active firms terminate (die)– 50 m. a year.
Massive medical research is underway to find cures for disease. I wonder why similar research is not undertaken to discover why 50 m. businesses ‘die’ yearly, and to discover remedies. Some may deserve to fold — but many may not.
The GEM study shows that one of the most basic motives for starting a business is “necessity entrepreneurs” — those who cannot find suitable work and start a business to survive. Necessity entrepreneurship seems to be growing worldwide in the wake of the global economic crisis. It is one of the few positive effects of the crisis.
[1] Mason cites a study by Brian Headd, U.S. Bureau of the Census, Business Success: Factors Leading to Surviving and Closing Successfully, working Paper #CES-WP-01-01, Jan. 2001).
Global Crisis Blog
The REAL Sovereign Debt Crisis
By Shlomo Maital
In general, the truth lies not IN the headlines, but behind them, in the back pages.
The sovereign debt crises in Greece, as well as in Ireland, Portugal, Spain, and before them, Iceland, capture the media’s attention. Because of bailout and fiscal stimuls spending, public debt as a percentage of GDP will exceed 110 per cent in 2014, in the G20 countries. Under Europe’s Masstricht Treaty, signed in 1992, 60 % was regarded as an upper limit. But an insightful brief article by Richard Barley, in the Global New York Times (Feb. 17) goes behind the headlines.[1] The REAL debt crisis, it emerges, lies elsewhere.
During the boom times of the ’90s and ’00’s, “recklessly generous social contracts offered to their citizens in the boom years [social security, health care, etc.]” created enormous contractual legal entitlement debts stretching 50 years into the future. These contracts, motivated by politicians’ desire to gain votes, represent irresponsible unforgiveable risk, because no government will be able to fulfill these obligations. Governments in the US, UK and elsewhere have misled their citizens, leading them to believe they will be ‘taken care of’ after retirement, when in fact the money for this will not be available. Compared to the reckless risk mismanagement of the banks, governmental risk mismanagement is orders of magnitude worse.
Here are the numbers. According to the International Monetary Fund (IMF), an impeccable source, as well as a study by economist Jagadish Gokhale for the U.S. National Center for Policy Analysis, the net present value of age-related deficit spending, as a per cent of GDP [i.e., the present value today of future pension and health obligations to retired persons ] is:
Greece 900 % Canada 600% US 500% UK 450% Portugal 500%
In other words, these governments have accepted such huge age-related commitments, that they will doubtless be unable to pay for them. If you are aged 50 or more, start saving. Those benefits you think you will get on retirement? Probably, you won’t get most of them.
Here is some simple economic analysis about how this age-related debt crisis will play out. * As governments try to pay for these expenditures by borrowing, they will issue increasing amounts of government bonds. (Politically, in the US social security is known as the ‘third rail’ for politicians — touch it and you die — after the electrified 3rd rail on train and subway rails). * Higher supply of bonds causes their price to fall, and yields (interest rates) to rise steeply.
If you are invested in government bonds, take into account that there will be tremendous long-run downward pressure on their prices. Another implication is inflation. Governments in the past escape burdensome debt by inflating the currency, reducing the real cost of that debt. Will they do this again? In an age of deflation, the shortsighted do not worry about inflation. Yet a future inflationary scenario is highly plausible, given the huge amounts of money now floating about in the system, and the debt scenario described above.
[1] “After Greece, the real sovereign-debt challenge”, IHT/Global New York Times, Feb. 17.
Global Crisis Blog
“Yes, We Can!” — But, Uhhh, Can We? And How?
By Shlomo Maital
All managers are familiar with the concept of “stretch goals” — setting ambitious visionary objectives, to energize the organization (for instance, President Kennedy’s “we will go to the moon by the end of this decade!”). The tricky part of stretch goals is to set them high enough to be energizing, but not so high as to be Don Quixotic, utterly impossible.
President Obama has promised to double US exports over the next five years, from $1 trillion to $2 trillion in 2015. This implies a 15 per cent annual rate of growth in exports. (He refers to goods exports, which amounted to $987 b. in 2009; services exports were another $480 b.).
Is this a stretch goal? Or another empty, impossible promise?
To answer that question, let’s see what it would take to make it happen:
* persuade the left wing of the Democratic Party to stop its efforts to impose tariffs and other protectionist measures. If America tries to halt imports, so will other countries — so much for US export expansion. Proposed free trade agreements with South Korea, Panama and Colombia are stalled, because of Democratic Party opposition, mainly from manufacturing states.
* allow the US dollar to drop steeply, by 30 per cent. This will cause a steep fall in US bond and equity prices, enraging the powerful special interests on Wall St.
* overcome the Wal-Mart bloc, which makes its profits through importing cheap products from China instead of buying US-made products.
* articulate a detailed practical trade policy. No such policy yet exists. Obama said he is starting a National Export Initiative that would “help farmers and small businesses increase their exports.” Does Obama understand that corn farmers in Iowa or plumbers in Utah do not themselves directly export their crops or services?
* Initiate legislation to bring American manufacturing home from Asia. No such legislation exists. I’m not aware even of draft legislation. Commerce Secretary Gary Locke, who will lead such an initiative, is the former governor of Washington State, and is a lawyer. He lacks the business experience and economics knowledge that is required for this to succeed.
* Woo China. America just signed an $8 b. deal to sell arms to Taiwan. To boost exports by 15 per cent yearly, America will need to sell its products and services to the fast-growing economies of India and China. But America has just greatly angered China. Typically, America’s Defense Dept. operates in direct contradiction to America’s Commerce Dept.
* Boost investment. To make globally-competitive products, America will need a huge wave of new capital investment in its industry. There is no sign whatsoever of such a wave; it depends crucially on restoring business profitability, and profits remain low.
* Curtail imports. If American imports double, as well as exports, nothing is gained; jobs lost to imports offset jobs gained by exports. But if imports are curtailed, why should other countries expand their purchases of American products?
* Solve the “rebalancing” problem. The world needs rebalancing — it has been knocked for a loop by huge American trade deficits. Creating a large American export surplus will not ‘rebalance’, but will create a new imbalance problem, impoverishing other countries.
* Boost saving. To free resources for exports, American consumers will need to spend less, and perhaps lower their standard of living, just as Germans, Japanese, Chinese and Indians did for decades. Does anyone believe this will happen?
Prepare for another Obama “we failed and here is why” interview, in TIME magazine, in three years. Perhaps Obama’s advisors should learn from business leaders. They know that before you launch a new “brand promise” campaign, you first build the foundations for it, so you can fulfill that promise. Before Staples launched its “that was easy!” campaign, they redesigned 1,500 stores, and retrained all their key personnel.
Obama consistently launches “yes, we can” rockets, and then wonders why they crash and burn.
How about a new slogan: Yes, we can! and here is how!
*** Footnote: Banner headlines scream “America’s GDP grew by 5.7 percent in the last quarter of 2009”. As I noted before in this blog, this is an optical illusion. Here is why. Final sales to domestic purchasers rose by only 1.7 per cent. That is the increase in what was actually SOLD. Most of the GDP that was produced in Q4 2009 was stuffed into inventory. The change in private non-farm inventories contributed 3.61 per cent of the 5.7 per cent GDP growth, or more than three fifths of the GDP growth! This implies that when businesses stop producing for inventory, GDP growth will fall sharply in 2010. (Source: Bureau of Economic Analysis, US Dept. of Commerce: New Release, Jan. 29/2010).
Innovation/Global Crisis Blog
Barclays Bank: Disruptive Management Innovation?
By Shlomo Maital
Clayton Christensen (Harvard Business School) became famous for his concept of disruptive technology: new technology that changes the rules of the game in industries.
Perhaps there is also disruptive management innovations. And Barclays Bank may be implementing one.
The BBC reports that Barclays will defer its bonuses to its 130,000 employees worldwide:
Barclays is to defer paying bonuses earned this year to its directors and senior staff for up to three years. The BBC understands the payments for last year have not been set, but when they are will be paid out mostly in shares in staggered form up to 2013.
Barclays did not receive any money directly from UK taxpayers during the financial crisis. However it did sell a notable share of its business to the government of Abu Dhabi. The bank will tell its 130,000 staff over the next few weeks that while they will be getting a bonus, almost all of it will be deferred over the next three years – and this will be the new ongoing policy.
Until now, American investment banks and some commercial banks have stubbornly insisted: Unless we pay huge bonuses to our top talent, they will quickly leave, join other banks, and make money for them rather than for us. High bonuses are an essential part of the banking landscape. No-one can endure or prevail without paying them.
Now comes Barclays, which took no UK government bailout money (though it did raise money from Abu Dhabi), and seems to be trying to change the rules of the game. By making bonuses payable in shares, over a 3-year period, they create incentives for less short-run risk-taking and more long-run profit-building.
Let us wish Barclays well. Their experiment is very important, far more important than the UK government’s 50 per cent windfall tax on bonuses, or President Obama’s windmill-tilting threat to break up large US banks. If Barclays succeeds, restores its financial health, makes sustained profits and thrives, and if Barclays manages to retain top talent (or, more important, attract top talent who believe in a more sustainable, long-run ethical approach to banking), it will comprise a disruptive management innovation that other more feckless banks may be forced to adopt.
Darwinian experiments of this sort are far more effective than government regulation.